

It wasn’t a surprise when Adcock Ingram, another reputable mid-sized company on the JSE, attracted a minority buyout proposal last week. Interestingly, the offer doesn’t come from its principal shareholder, Bidvest, but from a Mumbai-listed company called Natco Pharma.
The announcement contains the usual standardized reassurances, claiming the offer comes at a premium above the recent average share price, that an independent expert has assessed it as fair and reasonable, and that a committee of independent board members will endorse acceptance and delisting. Furthermore, they mention, “As a private entity, Natco and Bidvest plan to explore new revenue streams and broaden operations in one of Africa’s largest and fastest-growing markets.”
ADVERTISEMENT
CONTINUE READING BELOW
While I remain open to differing opinions, I believe these claims lack depth. We have invested in Adcock Ingram for over five years and recognize it as an outstanding enterprise backed by a credible and ambitious controlling shareholder, a robust executive team, and high governance standards. I see no legitimate reason why a listed Adcock Ingram would suddenly find itself unable to chase new revenue opportunities, nor why we couldn’t sustain long-term investment strategies on behalf of our fund shareholders.
Read: Adcock Ingram says no brand cuts planned after Natco deal
This discussion extends beyond Adcock Ingram; there’s a larger context that demands our consideration. It’s clear why several JSE-listed companies have either delisted or are in the process of doing so. While the contraction of stock markets is a global issue, it is particularly acute in South Africa.
This phenomenon can be traced to three main factors:
First, a mixture of regulatory measures and irresponsible actions from both public and private sectors have led to excessive direct and indirect costs associated with being publicly listed;
Second, persistent capital flight from the JSE since 2010 by both domestic and foreign investors has resulted in many stocks being significantly undervalued;
Third, a considerable number of retail and institutional minority shareholders seem willing to accept subpar offers to cash out, prioritizing immediate rewards over long-term value. Opting for short-term gains at the expense of valuable businesses is a myopic strategy.
It is crucial to highlight that the term ‘currently’ applies to these three points, as circumstances have changed in the past and could do so again in the future. I remain hopeful for improvement, thanks to inherent market self-correcting mechanisms.
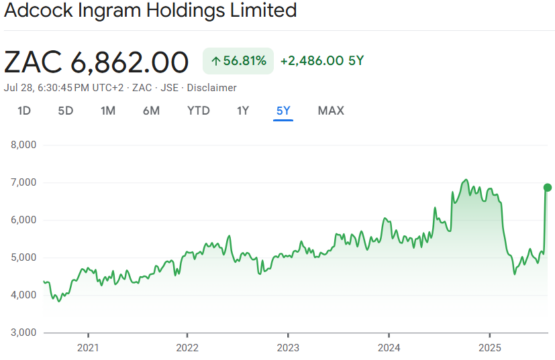
Source: Google Finance
Evidence indicates that a well-established, quality growth enterprise can be valued at around 15 times normalized after-tax annual profits. From an investor’s perspective, it’s crucial to acknowledge that at fair value, a business is expected to provide an ‘equity risk premium’ to future long-term minority shareholders. Additionally, it’s important to note that this equity risk premium signals a highly attractive anticipated rate of return, significantly surpassing that of lower-quality listed companies and various alternative asset classes (valuables, cash, government and corporate bonds, and real estate).
ADVERTISEMENT:
CONTINUE READING BELOW
Remaining listed also grants patient, valuation-conscious investors consistent long-term buying and selling opportunities that can greatly improve the expected equity risk premium return.
Should we ever accept an offer that falls below or aligns with fair value for any of our quality listed South African businesses? That seems irrational. Why would we, on behalf of not just ourselves but the broader South African investment community, willingly forfeit the substantial future return potential locked in a solid listed company like Adcock Ingram, solely to enrich a foreign entity that brings no tangible benefits to the South African economy or its populace? Such reasoning is nonsensical.
Read: Adcock Ingram says no brand cuts planned after Natco deal
We have no issues with any quality business opting for delisting, nor with the individuals or organizations facilitating such actions, as long as the offer price adequately compensates for the attendant downsides. If the offer is insufficient, the matter devolves into governance challenges, including minority rights and how minority shareholders will collectively choose to exercise their voting rights.
Our work continues ….
Daniel Malan is CFA, founder, managing director & CIO at Perspective Investment Management.
Follow Moneyweb’s comprehensive finance and business news on WhatsApp here.


