

A deeper insight into the Federal Reserve’s dedication to tackling inflation is prompting investors to adopt a more optimistic outlook, though apprehensions regarding oil prices and artificial intelligence are hindering their full commitment.
Last week, the Fed successfully reinstated its credibility, underscoring its alertness to inflation with a hawkish tone that did not explicitly suggest an aggressive interest-rate hike cycle. While this message initially calmed the markets, anxiety lingered on Friday as the 10-year Treasury yield approached 5% again, and the S&P 500 fluctuated between gains and losses. Even after a recent drop, Brent crude remains priced above $100 per barrel.
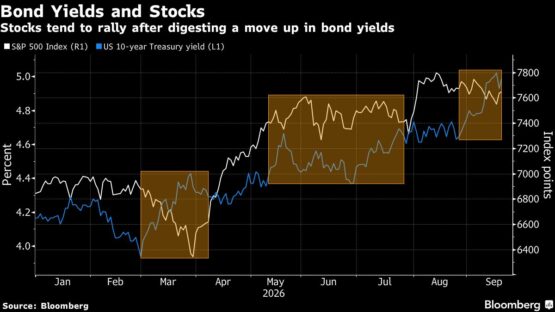
“It’s difficult to picture rates and equities reaching complete stability until energy-linked inflationary pressures diminish,” remarked Barclays Plc strategists, led by Emmanuel Cau. “However, the affirmation of the Fed’s independence and credibility is a positive development, clarifying its response function.”
The Fed’s recent actions can be considered a turning point. Investors approached the policy meeting with caution, signaling a clear reduction in risk exposure while enhancing their hedges. Moreover, Friday’s significant quarterly expiry was instrumental in resetting options positioning.
“With robust earnings growth, manageable credit spreads, and a low VIX, the fundamentals of US equity remain promising, leading us to have a positive outlook on the S&P 500 beyond short-term volatility,” stated Societe Generale SA strategist Manish Kabra. The yield curve remains a critical indicator, and as long as inversion is avoided, Kabra expects the benchmark to hit 8,000 by year-end, despite possible fluctuations.
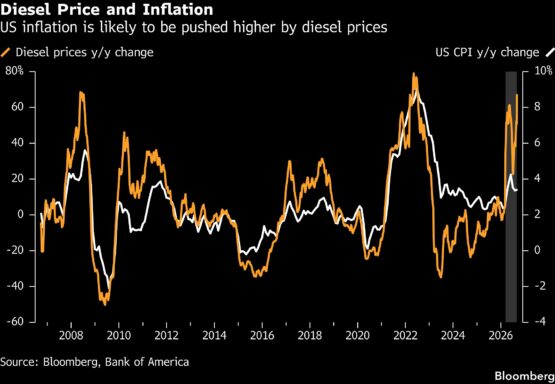
While a year-end rally seems achievable, the route may be fraught with challenges. Diesel prices suggest looming inflation, and without a swift resolution to the situation in Iran that substantially reduces oil prices, the central bank may find itself compelled to adopt an even more hawkish position.
ADVERTISEMENT
CONTINUE READING BELOW
The swap market suggests that three additional rate hikes are expected by the end of July. The focus is on a potential bond shock, with 10-year yields surpassing the 5% mark making Treasuries more attractive. Yet, as long as economic growth and earnings remain robust, investors may be reluctant to shift away from equities in favor of broadening their exposure.
Bank of America Corp. strategists, led by Jared Woodard, have taken a more cautious approach, asserting that positioning remains overly bullish considering the anticipated moderation in earnings for next year. They pointed out that the projected 10%-15% growth for 2027 implies an ISM manufacturing reading exceeding 53 for an extended period. It’s “not yet time for defensives, but concentrating on quality, value, and yield appears prudent,” they commented.
Market sentiment has turned increasingly skeptical regarding AI expenditures and the expected returns from these investments, raising doubts about the earnings outlook for the broader AI-related sector. Concurrently, a shift within technology has occurred, with software making a strong comeback while semiconductor stocks have stagnated over the last two months, becoming more volatile.
ADVERTISEMENT:
CONTINUE READING BELOW
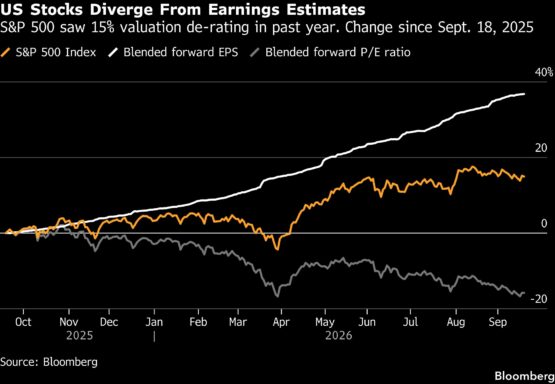
Valuations in the S&P 500 have seen a marked decline, with the benchmark now trading just above its historical average. This de-rating primarily stems from surging earnings forecasts, yet the recent downturn signals that investors are hesitant to pay a premium for growth, both at a market-wide and sector-specific level.
If caution prevails in the near term, an earnings season surpassing expectations in the forthcoming weeks could revive sentiment and encourage risk-taking.
“The resilience suggests that investors are distinguishing between rate hikes attributed to persistent inflation and a fundamentally declining growth outlook,” commented Daniela Hathorn, senior market analyst at Capital.com. “At present, the latter has not surfaced as the primary concern.”
© 2026 Bloomberg


